Summary
- The UK Space Strategy brings civil, commercial, defence, and security programmes into a single framework backed by £7.8 billion to 2030.
- Priorities include satellite communications, space-domain awareness, in-orbit servicing and manufacturing, and assured access to space.
- Public investment is being paired with liability and insurance changes intended to support a larger domestic commercial market.
The UK government has brought satellite communications, orbital surveillance, launch capacity, and in-space servicing into a single national strategy backed by £7.8 billion to 2030, treating space systems less as a collection of specialist programmes and more as infrastructure underpinning communications, defence, transport, research, and other parts of the economy.
The UK Space Strategy identifies four priority subsectors: satellite communications, space-domain awareness, in-orbit servicing, assembly and manufacturing, and assured access to space. Government also plans an integrated national satellite-communications system intended to improve resilience and support defence.
Existing spending commitments now sit within that framework, including £149 million for the European Space Agency’s Vigil mission, £85 million for the National Space Operations Centre, and £880 million for space-control and intelligence, surveillance, and reconnaissance capability.
Bringing those programmes together reflects the degree to which orbital infrastructure has become embedded in terrestrial activity. Communications, navigation, weather forecasting, financial timing, agriculture, logistics, energy systems, and emergency response all depend on satellites, while disruption in orbit can create consequences well outside the aerospace sector.
Satellite communications become strategic infrastructure
The proposed national satellite-communications system is one of the clearest expressions of the strategy’s resilience agenda. Modern connectivity increasingly depends on a mixture of terrestrial networks, subsea cables, and orbital systems, while governments want greater assurance around communications supporting defence, emergency response, and critical services.
Britain is pursuing that capability alongside wider European investment rather than in isolation. The EU’s IRIS² secure-connectivity constellation is moving towards deployment, while commercial low-Earth-orbit networks are increasingly being connected to terrestrial telecoms systems.
Techopia examined the transition of IRIS² from policy into infrastructure in August. The UK now faces a similar question over where sovereign capacity is necessary and where commercial or international networks can provide enough resilience without duplicating expensive assets.
That distinction will determine how far public procurement supports a domestic industrial base. Government contracts can provide early demand for technologies that are difficult to finance through private markets alone, but the sector becomes more sustainable when companies can also sell communications, sensing, servicing, manufacturing, and operational capabilities commercially.
Regulation joins the investment plan
The government is also changing elements of the financial regime governing space operations, recognising that insurance and liability requirements can determine whether unusual missions can raise capital. A more variable approach to orbital-liability limits is intended to reward missions aligned with security and sustainability priorities rather than applying identical financial treatment to every operator.
Liability will be waived for certain innovative missions launched before the end of 2030, including some in-orbit servicing, assembly and manufacturing, and lunar missions. Government also plans new approaches to third-party liability insurance and changes to requirements around decommissioning funds for constellation operators.
Reducing those barriers does not remove the underlying operational risks. Companies still need to manage debris, collision avoidance, cyber security, spectrum, safe disposal, and the possibility that failed hardware remains in orbit for years after a mission ends.
The regulatory balance will therefore be judged on whether it lowers the cost of responsible missions without transferring too much risk to the public sector. A country can attract operators by reducing liability, but the benefit is weaker if the resulting framework gives companies insufficient incentive to manage long-term orbital hazards.
Industrial policy reaches beyond launch
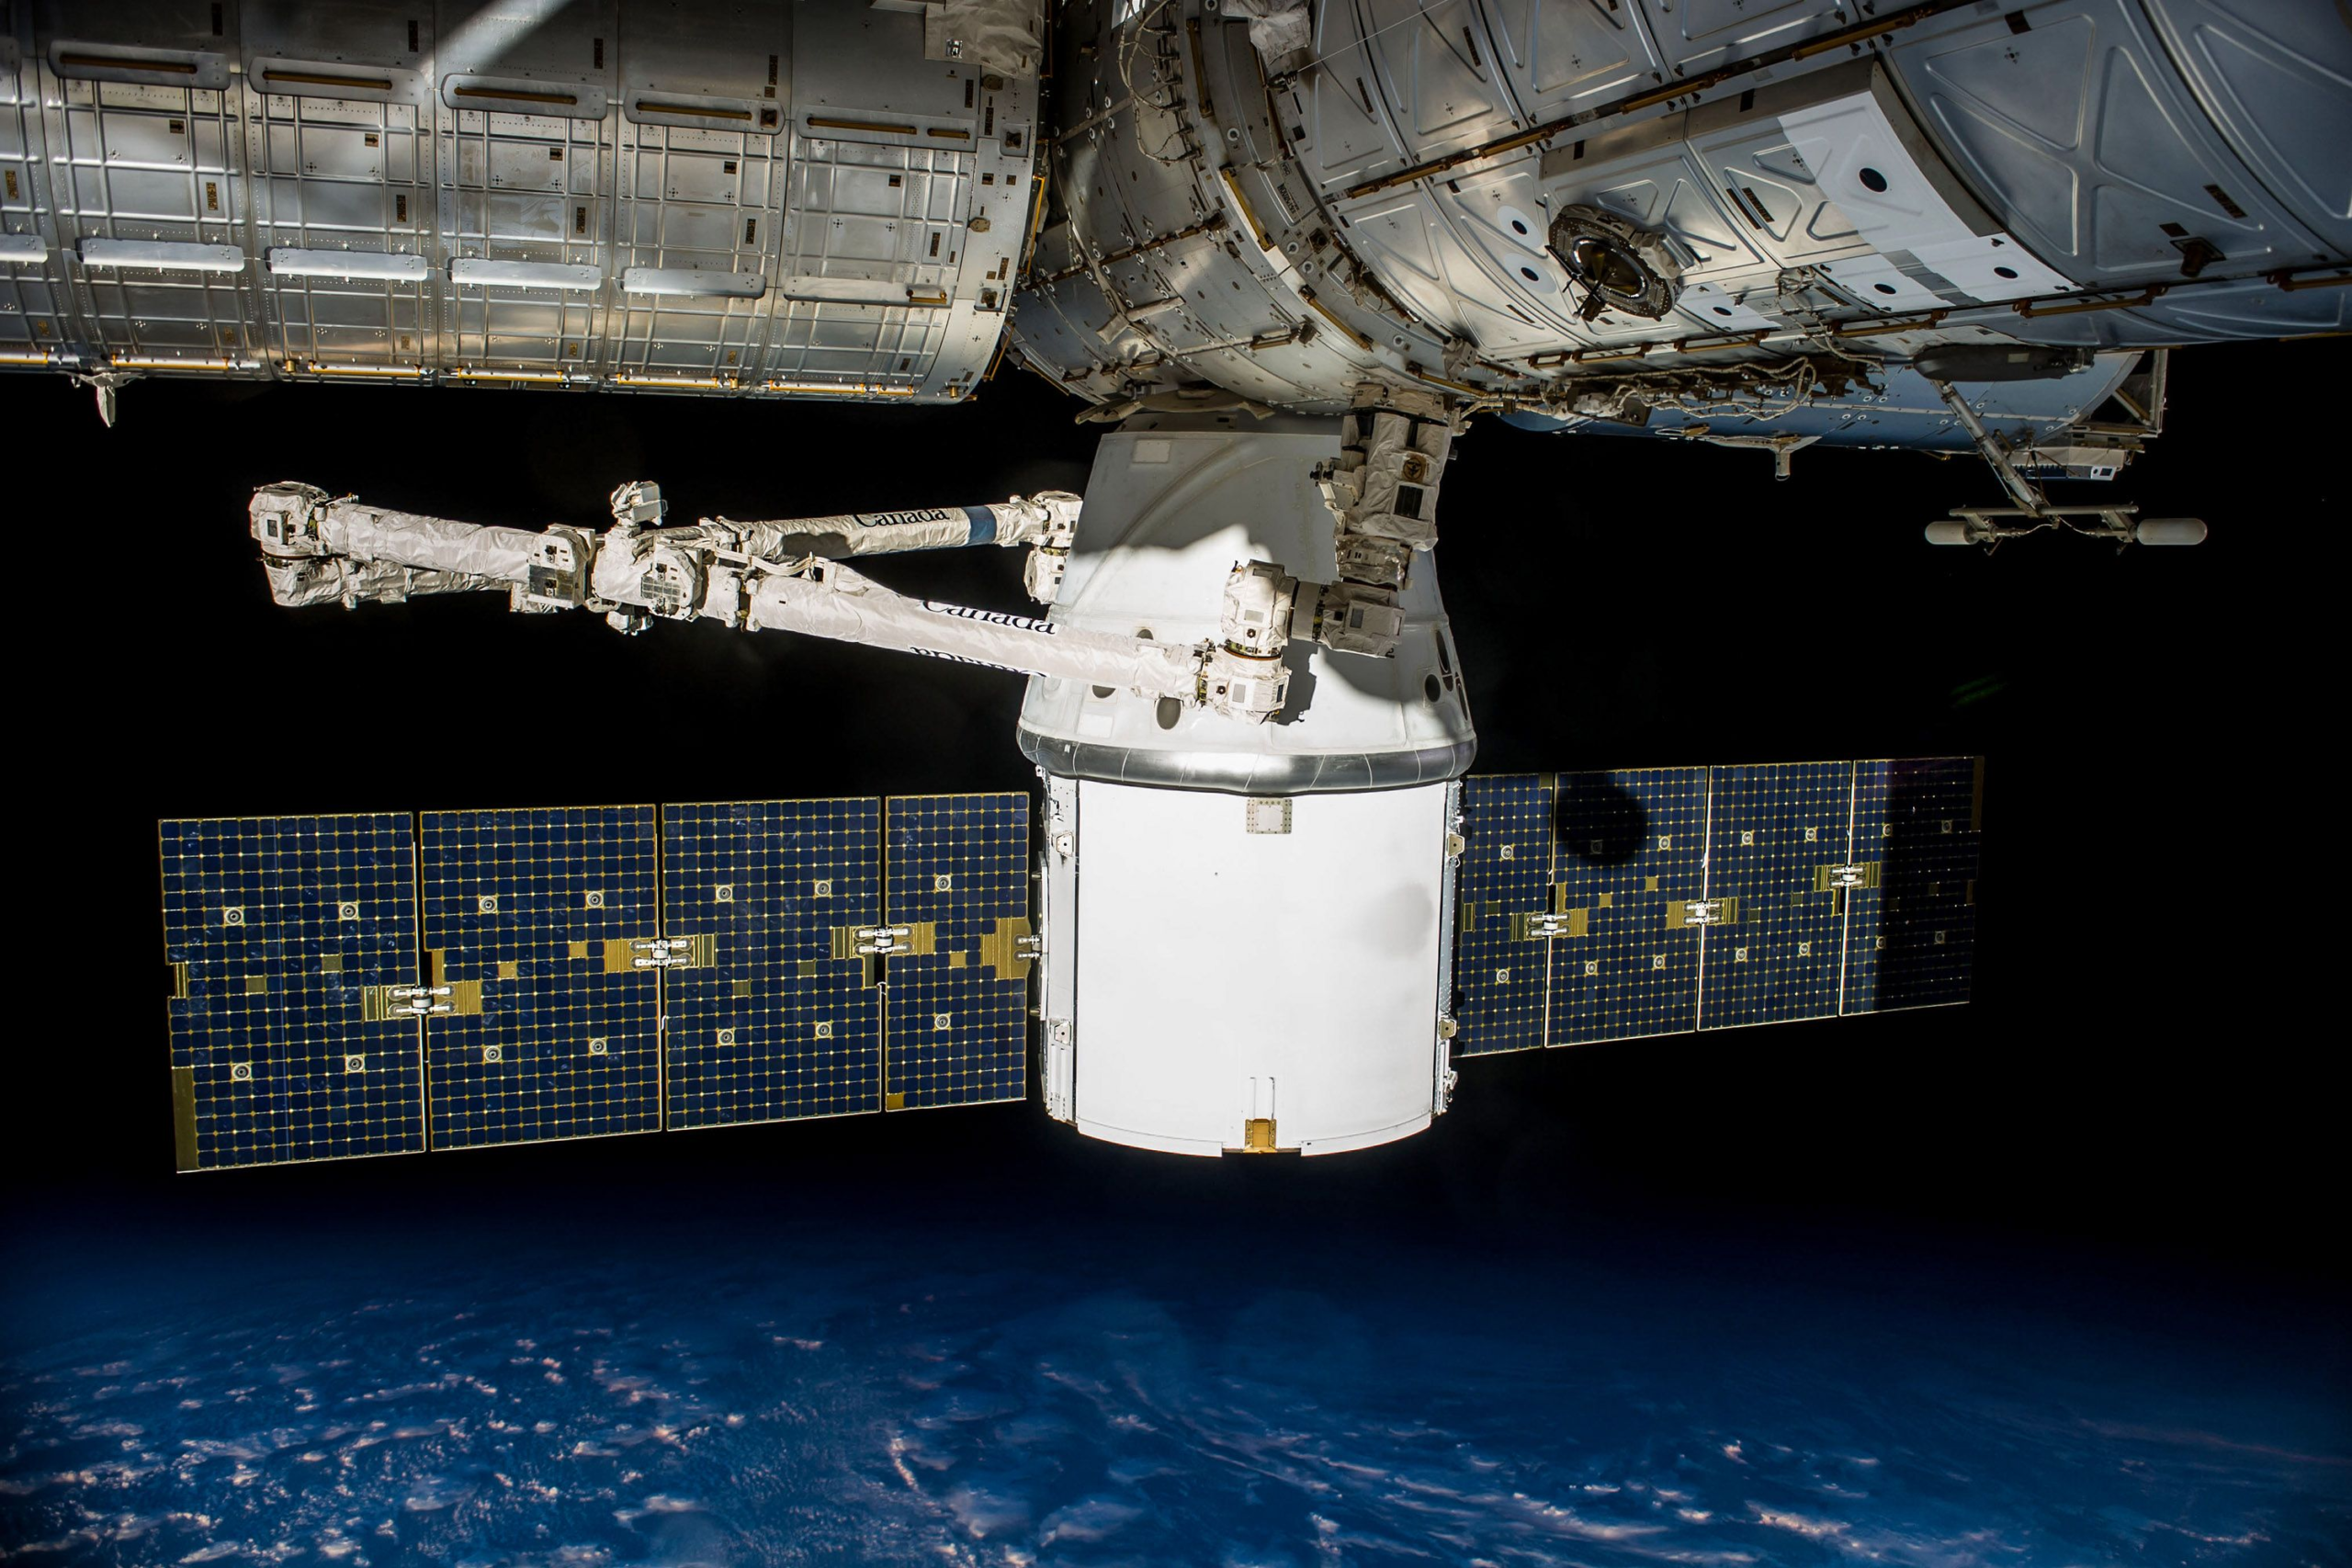
The focus on in-orbit servicing and manufacturing widens the strategy beyond rockets and conventional satellite production. Servicing could extend the useful life of spacecraft, while orbital assembly may eventually allow systems to be built without fitting every component inside the dimensions and mass limits of a launch vehicle.
Those markets remain technically immature, and commercial demand will depend on whether servicing a satellite becomes cheaper and more reliable than replacing it. Public demonstrations can establish capability, but sustainable businesses still need customers willing to buy the service without indefinite subsidy.
Assured access to space presents a similar challenge. Britain has invested in launch sites and domestic providers, while delays and capacity constraints across Europe have shown how quickly nominal sovereignty weakens when a mission is ready but a suitable launch vehicle is not.
Space-domain awareness becomes more valuable as those assets multiply because governments and operators need a clearer picture of satellites, debris, possible hostile behaviour, and environmental hazards such as solar activity. The £149 million Vigil commitment and National Space Operations Centre investment therefore sit inside the same resilience problem as communications and launch.
The £7.8 billion headline gives the strategy financial weight, but industrial outcomes will depend on procurement, programme discipline, and whether smaller suppliers can compete alongside established aerospace and defence contractors. Stable requirements can support investment, while contracts that change repeatedly or favour only incumbents can undermine the same domestic capacity the strategy is intended to create.
By 2030, the useful measure will be whether Britain has more resilient communications, regular access to orbit, functioning in-space capabilities, and commercial suppliers able to survive beyond individual government projects. The strategy provides a clearer map of those priorities; delivery will determine whether they become infrastructure.